Will Fabius Maximus Offer A Thorough Analysis?

by Smitty

Fabius puts up a post, “Will people on the right help cut Federal spending?“, that could have as easily been entitled “Will Lopping The Heads Off Of Dandelions Improve The Lawn?”

Fabius, the debt and deficit we face are rooted in the Federal government undertaking non-Federal tasks. Realizing that chronic deficit spending is unethical is a crucial corner to turn, or acute reductions in budgets will remain smoke, mirrors, and gimmickry. Until the economy catastrophically ‘splodes.

Fabius asks:

Will the people on the right, aflame with deficit-cutting fervor, cut the 25 – 30% of the government’s budget spent on defense (DoD, nukes, vets, pensions, foreign intelligence)? Without doing so it’s unlikely the budget can be balanced. . .

Yes, the DoD should feel the axe, particularly in the acquisition realm. Vets, not so much.

However, Defense remains a Constitutional, Federal task. So, until you figure out a way to de-globalize the economy, and re-orient the US away from being Team America: World Police (TAWP) (not a bad idea, but not one that can be achieved as quickly as Ron Paul would like), look for the build-down to go slowly.

Let’s double down on the point, since Fabius mentions Eisenhower: the National Security Act of 1947, too, is a part of Progressivism that must come under scrutiny. Prior to the WWII buildup, the US never maintained substantial military forces between wars. We can argue about Teddy Roosevelt and the Great White Fleet as a precursor to the modern TAWP, and Alfred Thayer Mahan as the face that launched copious tonnage, but that underscores my point.

The transition away from the global military superpower toward whatever nuanced, yet-to-be-named, post-everything utopia will be a slow one. It’s taken over a century to dig the military money-pit. The world direction, politically, seems to want to be in the direction of centralization, with the League of Nations giving way to the perpetually flailing United Nations. The Information Age exposes the truth that these so-called Statesmen would be twice as effective if they were half as bossy, with a quarter of the legislation they sign.

Full circle, then: real improvement will come from mature, historical analysis of what the country is trying to achieve at what level. Historical analysis and Hayek show that vast power in the hands of few is neither traditional, nor healthy, nor (if we dare let the Constitution mean what it says) legal.

Obamanomics: No Jobs, No Recovery

Here’s a handy little chart showing the pattern of job losses in recessions since World War II:

That big red line is the current recession, and Scott Stoddard of Investor’s Business Daily explains:

Job recoveries have been increasingly sluggish over the past several recessions and the current downturn looks to be the longest since at least World War II. . . .
Today’s jobs slump, already at 29 months, could last five years or more, analysts say. Employers are expected to stay cautious amid a sluggish economic recovery.
“It would be strange but not inconceivable” for employment to fall short of its pre-recession peak before the next downturn, said Don Rissmiller, chief economist at Strategas Research Partners. . . .

OK, here come the magic words:

Rissmiller and other economists say a double-dip recession is unlikely. Yet hiring remains painfully slow. Excluding temporary hires for the 2010 Census, the economy has added about 500,000 jobs so far in 2010. The U.S. will need to add about 8 million jobs just to get back to the December 2007 peak, when the recession started.
Excluding the soon-to-disappear Census jobs, employers would need to average nearly 300,000 new jobs a month for the next 27 months just to get to the pre-recession peak by the end of 2012. . . .

Read the whole thing. Everybody keeps saying that a double-dip recession — that is, a “W”-shaped recession, instead of a “V” — is “unlikely.” Right, and if trends turn downward again, I’m sure that will happen unexpectedly.

Speaking of which, what about an unexpected debt crisis?

Former Federal Reserve Chairman Alan Greenspan said the U.S. may soon face higher borrowing costs on its swelling debt and called for a “tectonic shift” in fiscal policy to contain borrowing.
“Perceptions of a large U.S. borrowing capacity are misleading,” and current long-term bond yields are masking America’s debt challenge, Greenspan wrote in an opinion piece posted on the Wall Street Journal’s website. “Long-term rate increases can emerge with unexpected suddenness,” such as the 4 percentage point surge over four months in 1979-80, he said. . . .
“The federal government is currently saddled with commitments for the next three decades that it will be unable to meet in real terms,” Greenspan said. The “very severity of the pending crisis and growing analogies to Greece set the stage for a serious response.”

Don’t worry. I’m sure higher interest rates are as “unlikely” as a double-dip recession. Or the bursting of the Australian housing bubble. Wonder what’s up with gold prices?

UPDATE: Classic Obamanomics: Blame Republicans!

Another Friday, Another Bank Shutdown

The FDIC has gotten into the habit of announcing bank closures on Fridays:

Regulators on Friday shut down a Nevada bank, raising to 83 the number of U.S. bank failures this year.
The Federal Deposit Insurance Corp. took over Nevada Security Bank, based in Reno, with $480.3 million in assets and $479.8 million in deposits. Umpqua Bank, based in Roseburg, Ore., agreed to assume the assets and deposits of the failed bank.
The failure of Nevada Security Bank is expected to cost the deposit insurance fund $80.9 million.
With 83 closures nationwide so far this year, the pace of bank failures is more than double that of 2009 . . .
The number of bank failures is expected to peak this year and be slightly higher than the 140 that fell in 2009.

Bank failures are expected to be only slightly higher, but (a) we’re actually on pace for about 170 failures this year; (b) the commercial real-estate crisis is getting worse, not better, and (c) “unexpectedly” has become the MSM’s all-purpose adverb for bad economic news lately.

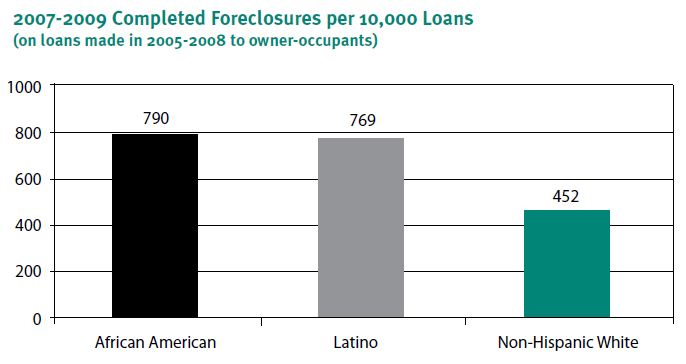
Meanwhile, a new report by the Center for Responsible Lending looks at “Foreclosures by Race and Ethnicity: The Demographics of a Crisis.” The report includes this handy chart:

So the foreclosure rate for Hispanic mortgage holders is 68% higher and the rate for black mortgage holders is 75% higher, in comparison to whites. The report goes out of its way to dismiss as “red herrings” any suspicion that the Community Reinvestment Act and the government-sponsored entities (GSEs) Fannie Mae and Freddie Mac had anything to do with this problem.

The conclusion of the report can be summarized this way: People who took out mortgages they couldn’t afford, thus allowing themselves to live (temporarily) beyond their means, were victims of unfair lending practices.

And you people who have limited yourself to only borrowing money you can afford to pay back? You’re chumps.

Ask yourself this: If Fannie Mae and Freddie Mac didn’t cause the foreclosure crisis, why does FDIC Chairwoman Sheila Bair say reforming the GSEs is a top priority?

For decades, the mortgage GSEs raised funds in global markets at preferred, near-government rates on the basis of their quasi-governmental status. For many years, this arrangement lowered the cost of mortgage credit to millions of homeowners without adding to the federal debt. However, in the aftermath of the mortgage credit crisis and the conservatorship of Freddie Mac and Fannie Mae, the implicit backing of these entities is now an explicit cost. Federal subsidies for the GSEs in 2009 and 2010 are estimated at over $300 billion.
In banking, the implicit backing of large financial institutions under the doctrine of Too Big to Fail led to moral hazard and excessive risk taking . . .
Our future financial stability demands that we deal with these implicit liabilities head on, and limit the ability of private companies to take risks at the expense of the taxpayer. In the case of the mortgage GSEs, there are a variety of options for making some of their functions governmental while putting others in private hands. But what we cannot do is perpetuate their quasi-governmental status, which privatizes gains and socializes losses.

So the free ride is over for Fannie Mae and Freddie Mac, at least if Sheila Bair has anything to do with it, but do you really think Chris Dodd and his fellow Democrats want to crack down on their buddies at Fannie and Freddie? Let me remind you of the names of the top three recipients of Fannie/Freddie campaign contributions, 1989-2008:

  • Chris Dodd . . . . . . . . . . $165,400
  • Barack Obama  . . . . . . $126,349
  • John Kerry  . . . . . . . . . $111,000

And a few other names from that list:

  • Harry Reid . . . . . . . . . $77,000
  • Hillary Clinton . . . . . $76,050
  • Nancy Pelosi . . . . . . . $56,250
  • Steny Hoyer . . . . . . . $55,500
  • Rahm Emanuel . . . . . $51,750
  • Barney Frank . . . . . . . $42,350

Fannie and Freddie have already cost taxpayers upwards of $300 billion, and heaven only knows what the final bill will be at the FDIC for this record-breaking year for bank failures, which might “unexpectedly” be worse than anyone yet imagines. One thing is for certain: Democrats are laughing all the way to the (taxpayer-subsidized) bank.

UPDATE: Welcome, Instapundit readers!

Alabama Radio Hosts Rick and Bubba Offend Soccer Fans Homosexuals

Rick Burgess: “I would dare to say that we would never declare Fornication Pride Month”:

Pam Spaulding is having a conniption. Just in case anyone wants to do a guilt-by-association smear, I’ll point out that Rick and Bubba are alumni of my alma mater, Jacksonville (Ala.) State University, as is James Joyner of Outside the Beltway. And JSU is home of the World’s Most Politically Incorrect Marching Band.

(Via Memeorandum.)

U.S. Robbed of Winning Goal in World Cup Soccer Game vs. Slovenia

Everybody knows soccer is for fags. Still, this doesn’t give anti-American referees the right to screw us over:

The United States staged the greatest rally in its World Cup history Thursday, overcoming a two-goal halftime deficit to record a 2-2 draw with Slovenia at Ellis Park.
Michael Bradley’s goal in the 82nd minute tied the game . . .
The Americans (0-0-2, two points) will face a must-win situation against Algeria on June 23. . . .
It appeared the Americans had pulled ahead in the 84th minute on a Maurice Edu goal off a Landon Donovan free kick, but referee Koman Colibaly apparently called a foul before Edu got the ball. . . .
“I still don’t know why the goal was disallowed,” Bob Bradley said after the match.

Yeah, well, I know why the goal was disallowed: Koman Colibaly hates America, that’s why. This is an international crime against truth and justice:

For the love of all that is holy! Those Slovenian scum were all over Bradley like it was pro wrestling! Some fag at Time magazine named “Sean” describes it:

On a free kick moments later, Landon Donovan delivered a beautiful ball into the box, which Maurice Edu knocked in to give the U.S. what looked like a historic victory. Gooooaaaal!!! But Coulibaly blew his whistle, and called a phantom foul on the Americans. The replay could not have been clearer: no infraction, the goal was legit. If anything, a hold on Bradley should have given the Americans a penalty kick . . .
ESPN commentator, and former Team USA defender, Alex Lalas called Coulibaly’s call “a disgrace.”

You’re damned right, it’s a disgrace. The CIA needs to capture Koman Colibaly, ship him to Guantanamo, and waterboard that terrorist bastard. Meanwhile, here is video of the schweet first goal by Landon Donovan:

Soccer is for fags and foreigners. Only our patriotic jingoism — USA! USA! USA! — gives us Real Red-Blooded Americans an excuse to pretend we actually care about the World Cup.

UPDATE: Dr. Rusty Shackleford is also a Real Red-Blooded American.

Obama to Europe: ‘Double-Dip,’ Anyone?

The headline is “Obama Urges Europe Not to Drop Stimulus Measures Yet,” but to understand what the president is actually trying to say, you have to read this New York Times story very carefully:

President Obama signaled on Friday that countries in Europe should not withdraw their extraordinary spending programs too quickly.
In a public letter to other leaders of the Group of 20 nations in advance of a summit in Toronto next week, Mr. Obama wrote, “Our highest priority in Toronto must be to safeguard and strengthen the recovery.” . . .
Mr. Obama also wrote, “We must be flexible in adjusting the pace of consolidation and learn from the consequential mistakes of the past when stimulus was too quickly withdrawn and resulted in renewed economic hardships and recession.” . . .
American officials are concerned that fiscal retrenchment by too many countries at once could imperil the global recovery.
Mr. Obama warned of the risks of a double-dip recession, which most economists consider unlikely but not impossible.
“In fact, should confidence in the strength of our recoveries diminish, we should be prepared to respond again as quickly and as forcefully as needed to avoid a slowdown in economic activity,” he wrote.

People who haven’t been paying close attention might not understand why Obama is saying all this. Obama, his advisers and the Democrats in general are firm believers in Keynesian economics, which prescribes deficit “stimulus” spending. But Germany isn’t buying that baloney. Bloomberg News explains:

While Obama endorsed restoring order to public finances in the “medium-term,” his focus on growth is at odds with that of German Chancellor Angela Merkel’s preference for budget cuts amid Europe’s debt crisis. Each strategy carries risks. Continued stimulus risks bondholder revolt over rising debt burdens, while spending cutbacks could tip the global economy back into recession.. . .
Merkel, the head of Europe’s largest economy, said June 11 she expects to have a “hard time” at the summit and that she will respond that “there is no alternative” to cutting the fiscal deficit.
Germany’s Cabinet this month backed budget cuts worth more than 80 billion euros through 2014, while French President Nicolas Sarkozy this week raised the retirement age and increased taxes.

Pay close attention to this part of the Bloomberg story:

Chinese officials said in Beijing today that they plan to use the Toronto talks to discuss responses to Europe’s sovereign debt turmoil while keeping the yuan’s value off the agenda. The yuan has been held at about 6.83 yuan to one U.S. dollar since mid-2008 to help protect China’s exporters, drawing threats of tariffs from among U.S. lawmakers.
Obama doesn’t mention China in the letter but maintains his position that China’s currency value should be determined by the market. “I also want to underscore that market-determined exchange rates are essential to global economic vitality,” he said.
Obama is facing domestic pressure from his own party to lean on China to raise the value of its currency. Lawmakers such as House Ways and Means Committee Chairman Sander Levin and New York Senator Charles Schumer, both Democrats, say a weak currency gives Chinese exporters an unfair advantage over their U.S. competitors and costs U.S. jobs.
Levin said yesterday that the value must be increased by the end of the summit. After the G-20 meeting, “if China does not act and the administration does not respond promptly thereafter, the Congress will act,” Levin said yesterday at a hearing.

The Bloomberg reporter doesn’t connect the dots here, but mention of a potential “bondholder revolt” and this trade issue with China are in fact connected.

China owns a lot of U.S. debt, and there seems to be an implicit bargain here: China will keep funding Obama’s deficit spending spree, so long as the U.S. keeps its markets open to Chinese goods. Under pressure from U.S. labor unions, however, Schumer and Levin are starting to talk like Smoot and Hawley, which would undo that bargain.

So we’ve got high unemployment with mind-boggling deficits as far as the eye can see, and the whole thing could unravel if China ever gets tired of buying U.S. debt. 

Gold just hit $1,262 an ounce. Mere coincidence, I’m sure.